

A deadlock can freeze a joint venture long before anyone says the word "crisis." If I were drafting or reviewing an alliance deal, I’d focus on four failure points first: tie votes, budget fights, missed milestones, and partner breach.
Here’s the short version:
- Governance deadlock is when the board or owners can’t approve a needed decision.
- Operational deadlock is when the business can’t move, even without a formal vote.
- The first line of attack is usually escalation to senior leaders, then mediation or expert determination.
- If that fails, the deal needs a clean exit path, such as buy-sell clauses, put/call rights, or termination and wind-up rights.
- The best time to solve deadlock is before signing by setting clear triggers, deadlines, and pricing rules.
A few numbers stand out. Many buy-sell clauses use a 30- to 60-day decision window. Mediation often runs 60 to 90 days. Expert determination may take only 2 to 8 weeks. Those time limits matter because delay can stall hiring, contracts, funding, and product launches.
Dealing with Deadlocks in Joint Ventures
sbb-itb-2fdc177
Quick comparison
| Issue | What it looks like | Usual first step | If it still fails |
|---|---|---|---|
| Board tie vote | 50/50 split on a reserved matter | Escalate to senior leaders | Buy-sell or other exit right |
| Budget or capital call fight | No approved budget, no cash agreement | Escalate, then mediation | Exit or default remedy |
| Missed milestone | Delay in launch, trial, or delivery | Expert review or mediation | Exit, breach remedy, or wind-up |
| Partner breach | One side does not fund, staff, or perform | Cure process and escalation | Call right, termination, or sale |
My takeaway: a deadlock clause should do two jobs at once. It should help the parties fix the problem, and if that does not work, it should move them to a clean split without months of drift.
That’s the lens I’d use for the rest of the article.
Where Alliance Deadlocks Usually Start
Alliance deadlocks often begin with repeated friction that the governing documents just can’t sort out. Over time, those pressure points turn into either governance deadlock or operational deadlock.
Board Tie Votes on Reserved Matters
Reserved matters are usually where governance deadlock shows up first. In a 50/50 joint venture, any decision that needs unanimous or supermajority approval gives each side an effective veto. So when the partners disagree on a reserved matter – something that can’t pass through ordinary board action – a single tie vote can bring the JV to a standstill.
These matters often cover the biggest calls a business has to make, including:
- changes to business strategy
- hiring or firing effective leaders
- entering new geographic markets
- licensing jointly developed IP
- taking on major debt
That’s also why they become flash points. These are the areas where partners are most likely to want different things.
The damage can hit fast. Picture a biotech JV where one parent wants to shift from rare-disease therapies to broader indications, while the other wants to stay with the original niche focus. A 2–2 board split can freeze the product roadmap and push FDA-related submissions back by six to twelve months, cutting into first-mover advantage. And the problem doesn’t stop with that one vote. A tie like this tells management, customers, and potential investors that the governance model isn’t working.
Budget Stalls, Capital Calls, and Missed Milestones
Budget approval fights, capital call disputes, and missed milestones are common triggers for operational deadlock. When the partners can’t agree on the operating budget before the fiscal year begins, management often has to keep the business running on the prior year’s approved spending levels. That usually means no new hires, no new marketing spend, and no capital projects.
A fight over whether to put $50 million into a new plant or data center can stop infrastructure work outright. That can lead to liquidated damages under EPC contracts and missed go-live dates for customers. In leveraged U.S. structures, lenders may also see an unresolved budget fight as a governance warning sign, then tighten covenants or hold back more credit.
Missed milestones tend to follow the same pattern. In tech and pharma JVs, milestones such as a beta release date or completion of a Phase II trial are often written into the JV agreement and tied to downstream licensing or customer contracts. If the partners disagree on how to handle a delay, and that response counts as a reserved matter, the board can deadlock over the response itself. The JV then stalls while overhead keeps piling up, with no clear path for development.
Partner Nonperformance and Breach
Deadlock doesn’t start only when the board can’t agree. It can also start when one partner stops doing what it promised to do.
A common example is chronic underfunding. One partner may delay payment or pay only part of its share of capital calls, while also failing to provide promised staff, assets, or services. That leaves the other side with a bad set of choices: cover the shortfall, slow down projects, or push default remedies. Each of those steps will often need board approval, which can deadlock if the underfunding partner’s directors block enforcement.
Exclusivity and IP breaches can play out the same way. If one partner is accused of backing a competing product or using jointly developed IP without authorization, the board has to decide what comes next – litigation, termination, or renegotiation. Those responses usually fall within reserved matters. So even when both sides agree there’s a problem, they can still deadlock on the fix. The board gets stuck on staff withholding, support disputes, and IP violations alike.
The longer the dispute stays alive, the weaker the alliance gets.
Once these pressure points harden, parties usually move to structured resolution or exit.
Resolution Options Before the Alliance Breaks
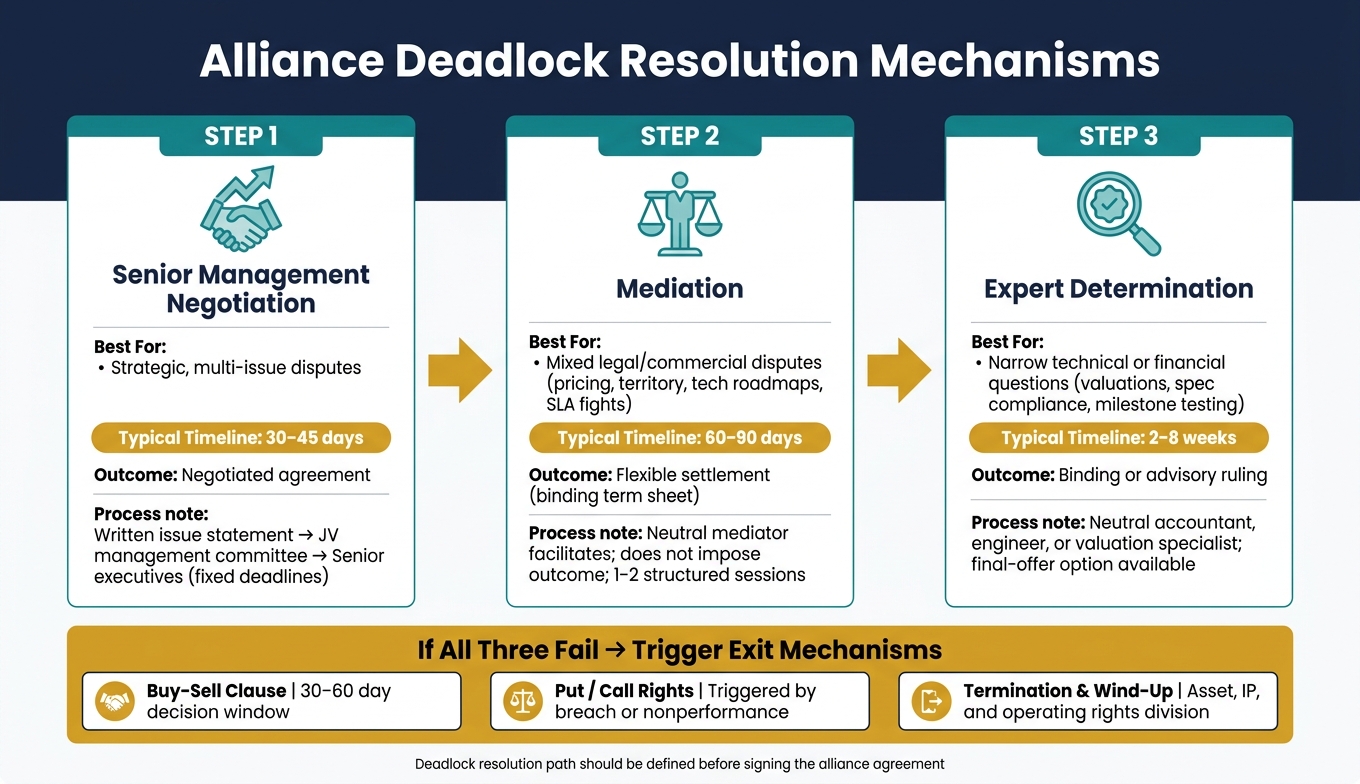
Alliance Deadlock Resolution: Mechanisms, Timelines & Best Use Cases
When board tie votes, budget delays, missed milestones, or nonperformance lead to deadlock, the first move should be a structured fix, not a breakup. In most deals, the path is simple: escalate the issue first, then try mediation or expert determination, and only then move to an exit right.
Escalation Ladders and Senior Management Negotiation
Start with a written issue statement. Then move the matter up from the working teams to the JV management committee or alliance steering committee, and then to senior executives, all on fixed deadlines.
That written statement does more than set the table. It clears up each side’s position, cuts down wasted time, and creates a record that can be used later in mediation or expert determination. Senior executives shouldn’t treat the meeting like a formality. They need to work the problem with tools like NPV models, market data, and scenario analysis.
Mediation for Multi-Issue Commercial Disputes
If escalation doesn’t get the parties there, mediation is usually the next step for disputes that blend legal rights with business judgment. A mediator helps the sides work toward a deal but does not force an outcome. That makes mediation a good fit for alliance disputes tied to pricing, territory rights, technology roadmaps, or service-level fights.
Mediation tends to work best when the alliance still has a point. A usual process takes 60–90 days and often includes one or two structured sessions. If the parties reach a deal, put it in writing right away in a binding term sheet or settlement agreement. After that, follow through with formal amendments to the JV agreement, including any governance updates or revised escalation steps.
If mediation doesn’t work, the agreement should already direct the parties to a neutral expert or an exit path.
Expert Determination for Technical, Accounting, and Valuation Disputes
Some deadlocks come down to a narrow technical or financial issue. In those cases, expert determination is often faster and more exact than mediation. A neutral accountant, engineer, or valuation specialist answers the specific question and gives a binding ruling if the agreement says so.
The trick is to keep the question tight. A neutral accountant can decide purchase price adjustments and profit-sharing calculations. An engineer or sector specialist can rule on spec compliance or milestone testing. Some agreements use a final-offer setup: each side submits its last number, and the expert picks one. That tends to push both parties toward more realistic positions. The agreement should also say whether the ruling is binding. For number-based disputes, binding is usually the better call.
These options are meant to keep the alliance in one piece. If they don’t work, the deal should shift cleanly to buy-sell and termination rights.
| Mechanism | Best For | Typical Timeline | Outcome |
|---|---|---|---|
| Senior management negotiation | Strategic, multi-issue disputes | 30–45 days | Negotiated agreement |
| Mediation | Mixed legal/commercial disputes | 60–90 days | Flexible settlement |
| Expert determination | Narrow technical or financial questions | 2–8 weeks | Binding or advisory, depending on the agreement |
If these tools fail, the agreement should move to buy-sell and termination rights.
When Formal Exit Mechanisms Become Necessary
When the relationship gets stuck, the contract needs to do one thing well: create a clean way out.
That’s what these tools are for. They deal with the same four breakdown points covered earlier: board deadlocks, budget disputes, missed milestones, and breach. Formal exit mechanisms – buy-sell clauses, put and call rights, and termination or wind-up provisions – exist for this exact moment. If the exit setup is weak, the dispute usually gets messier and more expensive.
Buy-Sell Clauses: Shotgun, Russian Roulette, and Sealed-Bid Structures
These clauses turn a deadlock into a transfer process with a price attached. The goal is simple: when the parties can’t run the business together anymore, one side exits and ownership gets sorted out. The difference is in how each method gets there.
A shotgun clause works like this: Party A names a price for the interest and offers either to buy Party B’s stake or to sell its own stake at that same price. Party B then gets a set decision window – usually 30 to 60 days – to decide which side of the deal it wants.
A Russian roulette clause follows the same basic setup, but it’s usually used for equal or near-equal partners and for stated deadlock events. Because the same price applies either way, the party that starts the process has a strong reason to name a realistic number.
A sealed-bid structure strips out the starter’s pricing edge. Both sides submit confidential bids, and the higher bid wins while also setting the purchase price. That can cut down on gamesmanship, but it also adds more process steps. And there’s a catch: bids can climb to levels that create financing trouble at closing.
No matter which structure the parties pick, the contract should deal with funding up front. That means spelling out proof of funds or escrow, along with firm closing timelines, U.S. dollar pricing, and what happens if the buyer doesn’t pay.
| Mechanism | Speed | Pricing Fairness | Complexity | Best For | Relationship Impact |
|---|---|---|---|---|---|
| Shotgun / Buy-Sell | Fast; often resolved within 60–120 days | Initiator sets price; fairness comes from the reciprocal buy-or-sell choice | Moderate | Equal or near-equal partners with similar capital access | Adversarial; ends the relationship with a clear outcome |
| Russian Roulette | Fast; often resolved within 60–120 days | All-cash price; responder can buy or sell at the same figure | Simple concept; drafting must cover financing proof and default consequences | Best suited to equal partners | Very disruptive; one party exits quickly |
| Sealed-Bid | Slightly slower because of bid administration | Both parties bid independently; higher bid wins | More complex; needs rules for submission and administration | Can work for unequal partners, but often favors the better-capitalized side | Final and neutral in process; still ends the relationship |
Put Rights, Call Rights, and Termination or Wind-Up Rights
Buy-sell clauses need both sides to take part. Put and call rights don’t work that way. They let one party act on its own once stated conditions are met.
A put right protects a minority holder that’s stuck in place. It lets that party force a buyout when the majority partner triggers a stated event. A call right does the opposite job. It gives the operating partner a way to force a buyout of the other side after breach or nonperformance. In both cases, the drafting should tie the right to clear triggers and cure periods.
Termination and wind-up rights sit at the last layer. These provisions govern how the venture ends, how assets and IP get divided, and which party keeps operating rights. IP needs extra care here. On exit, each partner should keep the IP and license rights it needs to continue operating.
Deadlock planning only works when the original deal spells out the triggers, pricing method, funding proof, and closing mechanics.
Prevention and Conclusion: Build Deadlock Planning Into the Deal
Exit tools only work if the agreement spells out the deadlock path from the start. The point isn’t to stop people from disagreeing. It’s to stop the business from getting stuck. So the best deadlock clause usually isn’t the one people use all the time. It’s the one written so well that everyone hopes it stays in the drawer.
Governance Design That Reduces Future Tie-Ups
The best way to avoid board tie votes and budget freezes is simple: set up governance in a way that makes both less likely.
An odd-numbered board is the easiest fix. A board with three, five, or seven directors will usually avoid tie votes. And if both sides want equal representation, they can appoint an independent director together to break ties on defined issues like budgets, strategy, or CEO performance.
Casting votes should stay limited to narrow operating issues. Big strategic calls should still need both sides to agree. In practice, that means the chair’s casting vote should apply only inside a preapproved range for things like annual budgets or small capital expenditures.
Reserved matters need the same discipline. Keep them focused on big decisions that can change the business in a serious way, such as new equity or debt issuance, M&A activity, and changes in business scope. Routine decisions should stay off that list. If the reserved list gets too long, the company can drift into constant gridlock, especially around budgets and board votes.
It also helps to build in a 12- to 24-month governance review. That gives the partners a set time to revisit reserved matters and board makeup as the venture changes over time.
Key Takeaways for Drafting and Leadership Practice
Define deadlock events, escalation deadlines, decision paths, and exit triggers in the deal itself.
Use expert determination for technical disputes. Use escalation ladders for strategic disputes. And for exits, set the funding terms, timing, and U.S. dollar amounts in advance. Then pressure-test the clause with a Year 2 missed-revenue scenario and a disputed remedy. If the contract doesn’t give a clean answer, it needs more work.
FAQs
How do I know if a deadlock is governance or operational?
Review your partnership agreement and your decision logs first. A governance deadlock usually starts when decision rights aren’t clear, escalation paths are missing, or the partners are aiming at different goals. In practice, it often shows up as repeated board-level fights over major investments, strategy, or how resources should be split.
An operational deadlock is different. It tends to center on day-to-day management, performance problems, or workflow slowdowns. If the issue comes back to people not following a pre-agreed delegation of authority, that’s a strong sign the problem sits in governance.
When should a JV use mediation rather than expert determination?
Use mediation when the main goal is to preserve the business relationship and find flexible, creative, or non-monetary solutions. It’s a collaborative, non-binding process, so both partners keep more control through open dialogue.
Use expert determination or arbitration when the dispute needs a final, legally enforceable decision or involves technical issues that call for an expert ruling.
What should a buy-sell clause include to avoid disputes?
A buy-sell clause should be clearly set out in the partnership agreement so there’s a clear exit path if the partners hit a dead end.
It should lay out the trigger events that can set the clause in motion, such as strategic stalemates, performance shortfalls, or financial struggles. It should also state, up front, how the company’s assets will be valued.
When these rules are defined in advance, there’s less guesswork, less tension, and less risk of day-to-day operations getting stuck.