

IPO messaging works when one clear story shows up everywhere: the S-1, roadshow, press release, deck, and management Q&A. If that story shifts, investors notice fast.
I’d sum up the article like this: tie the business plan to the numbers, explain risk in plain English, and keep every public message aligned from filing through listing. That matters because research cited in the article links better manager-investor communication to stronger early IPO trading results, with effects that can last up to 180 days after the offering.
Here’s the full checklist covered in the piece:
- Equity story: one simple message investors can repeat
- Growth narrative: show where future revenue should come from
- Risk disclosure: state the risk, the cause, and the response
- Why-now timing: explain why the company is going public now
- Management voice: sound measured, factual, and steady
- Message architecture: use one thesis with 3–5 support pillars
- Audience tailoring: keep the core story the same, but shift emphasis by audience
- Disclosure discipline: make sure numbers and claims match across materials
- IR infrastructure: build the systems, website, workflow, and Q&A library early
- Post-filing consistency: after the S-1 is public, let it guide every outside statement
The article’s main point is simple: IPO communication is not marketing. It’s a controlled IR process built to keep trust, reduce confusion, and avoid drift when scrutiny is highest.
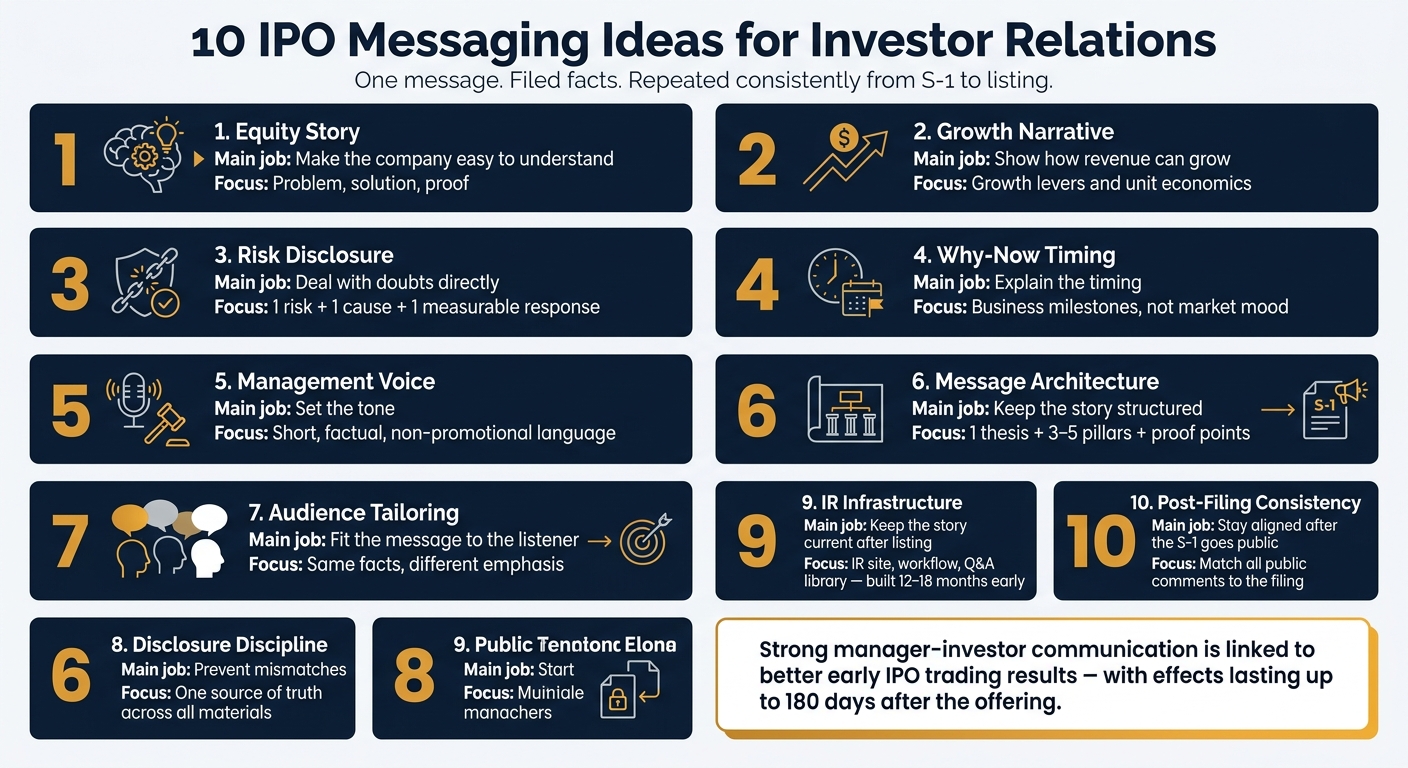
10 IPO Messaging Ideas: What Each One Does and How to Execute It
The IPO Wave. Get all the tips to maximize your IPO’s value by precise messaging, branding & Legal.
sbb-itb-2fdc177
Quick Comparison
| Idea | Main job | What to focus on |
|---|---|---|
| Equity story | Make the company easy to understand | Problem, solution, proof |
| Growth narrative | Show how revenue can grow | Growth levers and economics |
| Risk disclosure | Deal with doubts directly | Risk, cause, response |
| Why-now timing | Explain the timing | Business milestones, not market mood |
| Management voice | Set the tone | Short, factual, non-promotional language |
| Message architecture | Keep the story structured | One thesis, 3–5 pillars, proof points |
| Audience tailoring | Fit the message to the listener | Same facts, different emphasis |
| Disclosure discipline | Prevent mismatches | One source of truth |
| IR infrastructure | Keep the story current after listing | IR site, process, response control |
| Post-filing consistency | Stay aligned after the S-1 goes public | Match all public comments to the filing |
If I were preparing an IPO, this is the standard I’d use: one message, backed by filed facts, repeated the same way every time.
What Strong IPO Messaging Must Accomplish
IPO messaging has three jobs: connect strategy to results, spell out risk, and stay consistent across every channel.
Connect strategy to financial results: Show how the business model turns into revenue, cash flow, and earnings. Ground the story in numbers like net income, diluted EPS, and cash flow. That’s what helps investors see the link between the plan and the output.
Disclose risk clearly. Name the material risks, explain what caused them, and show how the company is responding. If goals were missed, say so plainly. Then explain what happened and what changes next.
"A frequent mistake that executives make when writing an annual report is making it sound too promotional and skipping the company’s obstacles over the year. However, you can make these obstacles a key point… and focus on how you plan to overcome them." – Jessica Fender, Professional Writer
Keep the message aligned across every channel. If one channel says one thing and another says something else, uncertainty creeps in fast and rumors can spread. The better approach is simple: treat investors like informed partners. Say what’s uncertain, back up what’s known, and let the data make the case.
With those rules in place, start with the equity story.
1. Equity Story
Build one message investors can repeat after the roadshow.
Your equity story sits at the center of the IPO. Every filing, deck, and press release should tie back to it. Then that same message should shape how you talk about the growth plan.
Keep it tight with a simple three-part frame: market context, customer problem, and your solution.
Back up every claim with clear metrics, like revenue growth, net income, diluted EPS, and cash flow. If you missed targets, say that plainly. Explain what happened and what will change. That kind of honesty builds more trust than a polished pitch that skips the rough patches.
The aim is one repeatable sentence: who you are, what problem you solve, and how you solve it. Once that core story is in place, the next step is showing how it grows.
2. Growth Narrative
Show investors where future revenue will come from, and why that growth story holds up.
Then make the levers clear. Spell out what drives growth: new customers, more spend per account, new products, or expansion into new geographies. Uber did this well by linking growth to a clear expansion path: ride-hailing, then delivery, grocery, and freight. That story gets stronger when the economics back it up.
Tie growth to unit economics and a path to profitability. For SaaS and tech issuers, stick to the metrics already disclosed in the filing. Keep the language plain. Skip vague terms like "rapid growth" or "market opportunity" unless they connect to specific, measurable claims already in your filings.
Once the growth case is clear, the next step is to disclose the risks without undercutting it.
3. Risk Disclosure
Be direct about risk without letting it drown out the growth story.
Investors put more weight on IPO messaging when management speaks plainly about risk and shows what the company is doing about it. The basic approach is simple: state the risk, explain the cause, and show the response. Stick to one specific risk, one clear response, and one measurable action that is already underway.
If a risk factor appears in your S-1, don’t copy it word for word. Address it head-on instead. Name the exact challenge, explain why it exists, and spell out the actions already in motion to deal with it.
Keep roadshow remarks and press releases in line with the S-1. Don’t add claims that aren’t already backed by the filing. Every risk statement should match the S-1, and every claim should be supported by filed disclosures. In plain English, the S-1, roadshow, and press releases should all say the same thing so the market hears one risk message from start to finish.
Once the risk case is clear, the next message is why this IPO is happening now.
4. Why-Now Timing
Tie timing to internal milestones, not market swings.
Once you’ve defined the risk, spell out why the company is ready to go public right now. The strongest why-now case starts inside the business. Point to the milestone the company has already reached, then show the next step the IPO will fund. Name the gap that still remains, and connect the IPO to the exact work, capital, and execution needed to close it.
Keep every claim grounded in the S-1, roadshow deck, and press release. That way, investors see the same timing story across all three.
Use that same why-now rationale in the S-1, roadshow, and press materials. When the message stays aligned across those channels, it reinforces the story throughout the filing process.
That same timing logic should shape how management talks about the deal, too.
5. Management Voice
Speak like a steward, not a pitchman.
The CEO and CFO set the tone for the entire IPO. Their language should be factual and measured, and it needs to match the S-1, roadshow, and press materials. That tone carries into every investor touchpoint, from prepared remarks to Q&A.
"A frequent mistake that executives make… is making it sound too promotional and skipping the company’s obstacles over the year." – Jessica Fender, Professional Writer
Acknowledge the gaps, then explain the plan. If management talks about missed goals, it should lay out the original target, why the company fell short, and what it will do to fix it. That isn’t spin. It’s a sign of discipline and control. Back those statements with exact numbers.
Keep management focused on two or three core messages, then repeat them the same way across every format. The same rule applies in roadshow Q&A: keep answers short, factual, and in line with what has already been said.
With the voice in place, the next step is shaping the message so each audience hears the same core story.
6. Message Architecture
Build one IPO framework: a single investment thesis, 3–5 supporting pillars, and proof points for each one. Then run the S-1, deck, press releases, and roadshow through that structure.
That framework keeps every claim, slide, and answer on the same script. It gives the story shape, so management isn’t saying one thing in the filing and another on the road.
Investors expect to hear the same core story across filings, decks, and roadshow remarks. If the message shifts from one format to another, people notice.
A practical tool here is a claim-to-evidence matrix. For each pillar, spell out the claim, the proof, the likely objection, and the answer. It’s simple, but it keeps the team honest. It also helps the CEO and CFO handle Q&A in a consistent way while staying within Reg FD and SEC rules.
Don’t use 7–10 pillars. That’s too many. When every theme sounds important, the main value drivers get blurry. Each pillar should be a short, testable claim backed by 2–3 metrics.
Mismatch between roadshow language and the filing can hurt pricing, so keep the wording aligned. Use the same structure as the base, then shift the emphasis by audience without changing the core claims.
7. Audience Tailoring
Shape the story for each investor group. The main equity story should stay the same, but the proof, wording, and level of detail should shift based on who’s listening.
Once the core thesis is set, match it to how each group thinks about risk and upside. Growth investors tend to focus on expansion and net revenue retention. Value investors look for durability and downside discipline. Analysts want model inputs and sensitivities. Retail investors need a plain-English view of how the business works and what could go wrong.
The key idea is simple: use one framework, then change the emphasis and depth by audience. The S-1, roadshow, and press materials each do a different job, but they should all rest on the same facts and definitions. Tailoring changes what you stress. It does not change the disclosure standard.
Retail investors now make up about 20.5% of daily U.S. equity trading volume, up from under 10% a decade ago. That means plain-English communication matters a lot more than it used to. But there’s a rulebook here. Any retail-facing plain-English summary must be filed as a free writing prospectus with the required legend. FINRA Rule 2210 says retail communications must be fair, balanced, and not misleading, with risk disclosure built into the same piece.
A good gut check: after the meeting, can each audience repeat the story in its own words? If yes, the tailoring is doing its job. And once you make the message audience-specific, every version still has to stay inside the same disclosure rules.
8. Disclosure Discipline
Say the same thing every time, in every document.
Once you tailor the story for each audience, stop changing the core wording. Before anything goes public, set ONE source of truth. Every figure and claim in the S-1, deck, press release, and roadshow remarks needs to match the filed data. Financials, business descriptions, and milestone claims should stay identical across materials. Your problem statement and key differentiators should also read the same way in every format.
Set up a formal review gate so legal and finance approve every investor-facing document before it goes out. That step helps catch mismatches before investors see them. It also keeps the team from drifting into mixed messages.
Use trained spokespeople for investor questions, and keep them inside the approved message. The tone should stay factual, not promotional.
With the message under control, the next job is building the IR infrastructure that keeps it current and consistent.
9. IR Infrastructure
Build a system that keeps your message accurate and easy to find long after the IPO.
Once the IPO story is set, the IR team needs to keep that story easy to access and up to date after pricing. Launch a dedicated IR website before your stock starts trading. Think of the site as your main hub for SEC filings, FAQs, decks, governance documents, stock data, and contact details. Every item you post should support the same approved investment case.
The website carries the message. The workflow keeps that message in line. Set up a clear IR process with one designated point of contact, usually reporting to the CFO, who routes investor and media questions through a single approved channel. Keep records of public communications, maintain a Q&A library, and make sure finance, legal, and communications follow one approval path and one response log so answers stay consistent and compliant.
Start building this 12 to 18 months before listing. That gives the team time to set up an IR CRM, run mock earnings calls, and put together a content calendar for roadshows, quarterly calls, investor days, and conferences. Those pieces matter because they keep the IPO narrative current after filing, not just before listing. They also make the handoff into post-filing updates much cleaner.
10. Post-Filing Consistency
After filing, the S-1 becomes the script for every outside-facing message.
Once the S-1 is public, every statement needs to line up with it on numbers, risk, and tone. That’s where many teams slip. Research on IPO roadshows found that roadshow materials often use more optimistic and less uncertain language than the SEC filing, and that differences in tone and uncertainty are negatively correlated with post-IPO returns. When public comments drift from the filing, trust starts to crack.
A prospectus-based message map helps keep everyone on the same page. Every spokesperson should use the same approved definitions, metrics, and wording. Lock the script before the roadshow starts, then run every update – press releases, roadshow decks, and investor meetings – through that same source. It sounds strict, but it keeps small wording tweaks from turning into disclosure gaps.
This isn’t just a communications issue. It can turn into a legal one fast. Facebook’s IPO-related litigation illustrates this directly: investors alleged the company failed to disclose materially adverse mobile revenue trends compared with its IPO materials. Public SEC filings are associated with a 16% increase in litigation risk between the registration filing and issuance date.
So the process has to be tight:
- Send all investor-facing materials through legal and IR review before release.
- Flag any language that goes past what the filing supports.
- Check each update against the approved message map.
- Push changes through one control path.
That’s how companies keep the IPO story from drifting once pricing gets close.
Conclusion
IPO messaging isn’t a marketing exercise. It’s a disciplined investor relations system that maintains focus that needs to stay steady from the first filing to the first day of trading and into the post-listing period.
Taken together, these ten ideas form one message investors can trust. Each one serves the same goal: turning IPO communication into one clear, repeatable message that stays intact from filing through listing. In an IPO, confidence comes from one message, told with consistency, backed by facts, and delivered without drift.
FAQs
How do you test if your IPO story is clear enough?
Measure clarity in two ways: how investors respond, and what they tell you directly.
Watch signals like:
- Meeting attendance
- Q&A participation
- Time spent reviewing your pitch deck
- Investor sentiment during Q&A
- Response times to investor inquiries
It also helps to ask for direct feedback on how clear the presentation felt. That way, you’re not left guessing.
Review these KPIs on a regular basis so you can sharpen your messaging. The goal is simple: make sure your growth plans, risks, and financial story stay clear, useful, and in line with what stakeholders expect.
What mistakes create message drift during an IPO?
Message drift during an IPO usually starts when teams say different things in different places. One version shows up in investor materials, another in media interviews, and another on the company website. That gap gets even bigger when a company tries to speak to each audience in a different way but doesn’t stick to one core message.
A few other mistakes tend to make things worse:
- Using language that sounds too promotional
- Glossing over obstacles instead of addressing them head-on
- Letting investor relations, marketing, and executive leadership work out of sync
The result? A story that feels scattered when it should feel clear and steady.
When should a company start building its IPO IR process?
A company should start building its investor relations process well before an IPO. That gives the team time to set up data collection, stakeholder management, and strategic messaging before the pressure ramps up.
It also gives the company room to track results, tie key milestones into a clear equity story, and build steady communication channels that support long-term trust.