

Most JV problems start after the deal is signed, not before. I’d sum up the article this way: if you want to cut the odds of deadlock, cash fights, data leaks, and court battles, you need to lock down 7 controls before signing: partner checks, decision rights, funding rules, exit terms, data limits, board rights, and dispute steps.
The article points to a few hard numbers that set the tone: JV failure rates are often put at 50%–70%, only 9% of JVs in one review had strong governance, and just 27% of 50:50 JV agreements in one study included an exit or termination option for deadlock. That tells me one thing: vague drafting is expensive.
Here’s the short version of what readers need to look for before a deal closes:
- Partner due diligence: confirm finances, litigation, sanctions, ownership, and funding ability
- Decision rights: spell out who controls day-to-day issues and which items need board or owner approval
- Cash controls: set capital call rules, bank authority, approval limits, and default remedies
- Exit terms: define transfer limits, pricing method, deadlock exits, and change-of-control triggers
- Data rules: assign IP, customer data, derived data, use limits, and post-termination duties
- Board rights: lock in seats, quorum, voting thresholds, reporting, and reserved matters
- Dispute paths: set escalation steps, deadlines, forum, governing law, and injunctive relief rules
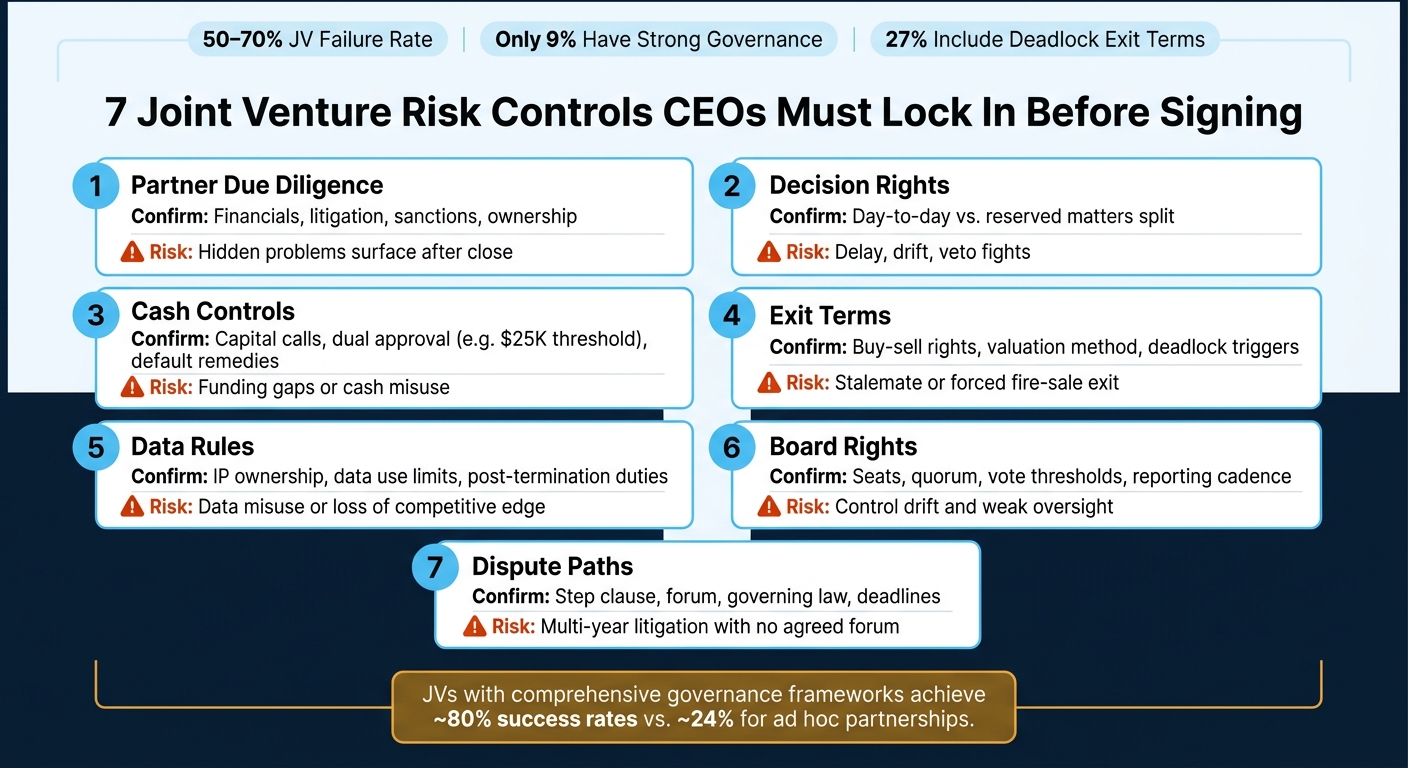
7 Joint Venture Risk Controls: What to Lock In Before Signing
JOINT VENTURES: Why Most Fail (And How to Do It Right)
sbb-itb-2fdc177
Quick Comparison
| Control | What I’d confirm fast | Main risk if weak |
|---|---|---|
| Partner checks | Financial, legal, regulatory, ownership review | Hidden problems show up after close |
| Decision rights | Clear split between management and reserved matters | Delay, drift, veto fights |
| Cash controls | Capital calls, signers, payment limits, remedies | Funding gaps, misuse of JV cash |
| Exit terms | Buy-sell rights, transfer limits, valuation method | Stalemate or forced bad exit |
| Data rules | IP ownership, access, use, deletion, audit rights | Data misuse or loss of edge |
| Board rights | Seats, quorum, vote rules, reports | Weak oversight and control drift |
| Dispute paths | Step clause, forum, law, deadlines | Long and costly litigation |
If I were reviewing the draft, I’d mark every approval threshold, funding duty, transfer limit, deadlock trigger, and data-use rule before legal comments start.
Why These 7 Controls Matter Before Signing
The issue comes down to timing.
One governance study found a median JV score of just 5.4 out of 10, and only 9% of JVs were rated as having strong governance. That’s why CEOs need to lock in governance terms early, before commercial momentum builds and those terms get much harder to change.
These seven controls need to work as a package. Pull one out, and the others lose weight. Weak diligence, fuzzy board rights, and no deadlock path can feed off each other fast.
Take one example: broad veto rights without a deadlock path can bring the JV to a standstill. In a study of 50:50 JVs reviewed by Harvard Law School‘s Corporate Governance group, only 27% of agreements included an exit or termination option for sustained deadlock.
That’s the point. These controls should be negotiated together before the letter of intent is signed and before the pressure to close peaks.
Begin with partner due diligence, because every other control rests on the counterparty’s reliability.
Quick-Scan Risk Control Table
Use this table to review the draft before you meet counsel. Mark each row green, yellow, or red. Then deal with every non-green item first.
| Risk Area | What to Verify in Drafts | Likely Failure if Weak or Missing |
|---|---|---|
| Partner Due Diligence | A due diligence memo or exhibit covers financials, litigation, regulatory status, and funding capacity. | Hidden financial weakness or legal issues surface after signing. |
| Role Split and Decision Rights | The agreement assigns control over strategy, operations, hiring, budgets, major deals, veto rights, and reserved matters. | Decisions stall and the JV drifts with no clear authority. |
| Cash Controls and Funding Rules | Funding duties, capital call timing, approval limits, bank signatories, and default remedies are defined. | A partner skips funding; the JV needs emergency financing or personal guarantees. |
| Exit Terms and Transfer Limits | Each partner has a defined exit right, valuation method, and U.S.-dollar payment terms. | Valuation disputes lead to stalemate, litigation, or a forced fire-sale exit. |
| Data Rules and Confidentiality | IP ownership, data use, customer access, and post-termination confidentiality are expressly assigned. | A departing partner copies customer data or proprietary tech; competitive advantage erodes. |
| Board Rights and Oversight | Board seats, appointment rights, meeting cadence, quorum, vote thresholds, and reporting rights are specified. | Weak oversight allows underperformance or misconduct to go undetected. |
| Dispute Paths | The contract sets escalation steps, governing law, venue, and resolution deadlines. | Minor disagreements escalate into multi-year litigation with no agreed forum or timetable. |
If a row turns red, fix the matching clause below before moving on.
1. Partner Due Diligence
Partner due diligence usually shows up in representations and warranties, disclosure schedules, and closing conditions. That’s where each side says its disclosures are accurate. If those statements later prove false, you may have a claim you can enforce. So this material shouldn’t just sit in a data room. It should shape control rights, funding caps, and exit terms.
Before signing, check audited financial statements for the last three years, litigation history, regulatory and sanctions history, and beneficial ownership. In a JV, plain acquisition diligence isn’t enough. You’re not just buying an asset and walking away – you’re running a business together. That changes the stakes.
Reference calls with prior JV partners or major customers can bring out problems the documents don’t show. A clean file can still hide messy facts. The goal isn’t only to learn about the other side. The goal is to turn what you learn into enforceable terms in the draft.
Investigative diligence can uncover state ties or other hidden control risks.
The JV can inherit the partner’s hidden problems. Hidden debt, regulatory exposure, or poor compliance can land on your side after signing.
Use what diligence turns up to tighten reps, warranties, covenants, and closing conditions before you sign. Once the partner clears diligence, the next step is to spell out who gets to make which decisions.
2. Role Split and Decision Rights
After partner checks, lock down who can act alone and who needs sign-off. Once diligence clears the partner, set out who runs each function. These rights usually sit in the JVA, shareholders’ agreement, or operating agreement, often with a decision-rights schedule attached.
Split day-to-day calls from reserved matters. Routine decisions like vendor selection, hiring below the C-suite, and spending within approved limits should sit with management. Reserved matters, such as major capital expenditures, issuing new equity, appointing or removing the JV CEO, or dissolving the JV, usually need board or shareholder approval, often by supermajority or unanimous consent.
Before signing, keep the reserved matters list specific and tight. Vague wording like any material decision is a red flag. It can slow normal operations and open the door to fights later. The JV CEO also needs enough room to run the plan day to day. And if the structure is 50/50, there needs to be a clear tie-breaker, like:
- an independent director
- a rotating casting vote
- a defined escalation path
Without clear decision rights, the CEO slows down and the partner gets more leverage after signing. If the JVA, shareholders’ agreement, and operating agreement say different things, you end up with avoidable gray areas. That split then feeds straight into cash authority and funding rules.
This is where deals often jam up. Partners can clash over pricing, product, or large contracts. Sometimes one partner starts acting outside its remit. When that happens, the result can be missed opportunities, costly settlements, wind-downs, or forced buyouts.
Before the final draft, ask for a decision-rights matrix attached to the JVA as a schedule. It should spell out the lead partner for each major function, including sales, operations, technology, and finance. It should also name the decision owner by role, set spending authority, and show the escalation path when a decision crosses the agreed threshold. Attach that matrix before signing so funding, oversight, and escalation rights line up.
3. Cash Controls and Funding Rules
After decision rights, cash authority is the next big control point. If cash controls are loose, one partner can move money without sign-off, skip capital calls, or even pledge JV assets as collateral before the other side has any idea what happened.
The capital call process needs to be spelled out in plain terms. The JVA should say:
- who can issue a capital call
- how much notice must be given
- whether contributions are pro rata to ownership
- whether there’s a cap per call or per year
Right next to that, set treasury authority. That means which bank holds JV funds, who controls the account, and when dual approval kicks in. For example, wire transfers above a set threshold, such as $25,000, should need two approvals for larger payments.
This matters because a controlling partner can misuse cash in quiet ways. It might use JV funds to support its own business, overbill through related-party vendors, or borrow against JV assets without any formal sign-off. The I-4 Ultimate highway JV dispute shows how ugly this can get: in April 2026, the Eleventh Circuit affirmed roughly $79 million in damages plus interest against the partner that refused to fund mandatory capital calls, and the non-defaulting partners had to cover the shortfall to keep the project moving.
You also need clear remedies for missed funding. That can include dilution, suspension of voting or dividend rights, or a forced buyout based on a pre-agreed formula. If the funding language is vague, you may end up with no enforceable payment duty and no clean remedy. Cash default rules also shape transfer limits and exit mechanics.
Make these finance controls impossible to overlook. Put them directly into the JVA’s capital contributions, funding, and banking sections. Back them up with board resolutions that set the banking mandates. It also helps to attach a finance schedule to the JVA that lays out the approval matrix by dollar threshold and the reporting cadence:
- monthly cash flow reports
- quarterly management accounts
- annual audited financial statements
- audit rights
4. Exit Terms and Transfer Limits
After you set the funding rules, the next issue is simple: what happens if a partner wants out? Exit terms and transfer limits spell out how that partner leaves, how the stake gets priced, and who gets the right to buy it. If these rules are weak, you can end up stuck with a partner you no longer want, or suddenly sharing control after an ownership shift.
The main terms usually sit in the shareholders’ agreement or operating agreement. The big ones include put and call options, drag-along and tag-along rights, buy-sell clauses, ROFR, and ROFO. Drag-along rights stop one holder from blocking a full sale. Tag-along rights stop minority holders from getting left behind on worse terms. And without ROFR, an outside party can step in without your consent.
Before signing, check four things:
- Lock-up period
- Valuation method
- Exit triggers
- Consent thresholds for third-party transfers
One clause deserves extra attention. If a parent company goes through a change of control, that event should be treated as a restricted transfer or an exit trigger, not as a routine affiliate transfer. And the language should reach indirect ownership changes, not just direct share transfers. That gap can cause trouble fast.
Weak exit terms often lead to stalemate and lost value. A buy-sell clause, sometimes called a "shotgun" clause, can break a deadlock: one partner sets the price, and the other must either buy or sell at that price.
Next, protect the data and IP that stay behind after a partner exits.
5. Data Rules and Confidentiality
After exit limits, data control is the last big safeguard that needs to stay in place when a JV falls apart. Put data and confidentiality terms in every JV document, and tie them back to one shared definitions section so the language stays consistent.
At the center of this sits the main clause. It should define confidential information, personal data, and analytics derived from JV data. It also needs to spell out who owns pre-existing data, JV-generated data, and derived outputs. From there, the clause should make clear who gets access, why they get it, what they can do with it, and what they can’t. It should also cover data protection and security rules, plus limits on sharing with affiliates or third parties. In many deals, confidentiality duties last 3–5 years after termination, while trade secrets stay protected with no end date.
That isn’t just legal housekeeping. Third parties are one of the biggest leak points, and the risk is expensive. Verizon‘s Data Breach Investigations Report found that 30% of confirmed data breaches involved third parties, up from 15% the year before. IBM‘s 2024 Cost of a Data Breach report says the average cost of a third-party breach is more than $5.08 million.
Before signing, check four redline items:
- Definitions of confidential information, personal data, and JV data
- Allowed and blocked uses, including whether data can be used in other business lines or to train AI models
- Access and security rules
- Post-termination return, deletion, audit, and notice rights
The biggest hole usually comes from indirect access through affiliates, contractors, subsidiaries, and advisors. If the clause binds only the JV entity, but not everyone the JV lets handle the data, you’ve left the back door open. Every confidentiality clause should apply to any person or entity given access, with tight need-to-know limits inside the organization and clear rules on onward disclosure.
6. Board Rights and Oversight
Once the role split is settled, board design decides whether oversight stays even. If governance is loose, control can drift after signing. And that usually happens in quiet ways: through management appointments, access to data, or decisions that never should have left the boardroom. That’s why board terms matter before the deal is signed. After closing, they’re much harder to change.
Board composition, voting rights, and reserved matters should line up across every governance document. If the papers say different things, trouble starts fast. The same goes for any negotiated veto rights or information rights. If one document includes them and another doesn’t, you’re setting up an argument later.
Before signing, check four points:
- Board seat allocation
- Chair selection and casting vote rights
- Reserved matters
- Board reporting cadence
It also helps to draw a clean line between routine management and board-level approvals. The reserved matters list should cover budgets, capex, new debt, related-party transactions, business-scope changes, and CEO appointment or removal. Put dollar thresholds on capex and financing items so the board spends its time on decisions that actually move the needle. Regular reporting gives the non-managing partner a way to spot trouble early, before it turns into a fight.
The data here is hard to ignore. A review of 101 large JVs found that only 9% had strong governance, while 41% were rated weak and 4% critical. The median governance score was just 5.4 out of 10. Clear governance makes JVs about 26% more likely to meet or exceed initial performance targets. Board design isn’t paperwork for the closing binder. It shapes how power works day to day.
If you skip this step, the danger isn’t only deadlock. It’s control shifting without anyone saying so out loud. One partner’s management team starts making calls that belong to the board. Budgets get changed without approval. Related-party deals slide through. At that point, the harm is already done, and the dispute may head toward litigation or an exit process.
A few guardrails can help stop that drift:
- An audit or risk committee with one financially experienced member
- productive quarterly meetings
- A standard reporting pack
When the board rules are firm, the last backstop is a clear dispute path for the moments when the partners still hit deadlock.
7. Dispute Paths
Even well-built JVs run into points where the partners just can’t agree. The difference between a problem you can work through and a total breakdown usually comes down to one thing: does the contract spell out what happens next? That document is the backstop when voting rights, funding rules, or exit terms stop doing the job. Without it, a dispute can turn into deadlock, a funding default, or data misuse that neither side can stop.
Use a tiered dispute resolution clause – often called a step clause – in the JVA, operating agreement, or shareholders’ agreement. Start with effective leaders negotiating, then move to executive escalation, mediation, and then arbitration or litigation. Keep each step on a short clock, usually 10 to 30 days. A research sample of international joint venture contracts found that 76.4% include arbitration provisions, which tells you how common arbitration is in JV deal design.
Before signing, check five points:
- the escalation steps and timelines
- the choice of governing law and forum
- whether disputes go to arbitration or litigation
- which claims can go straight to court for an injunction
- how legal costs are allocated
For U.S. deals, Delaware or New York are common choices. It also helps to pressure-test the clause with counsel against a funding dispute or a technology-misuse claim. If you don’t lock down the forum and governing law, each partner may file in a different court and set off conflicting orders. And public court litigation brings another risk: filings can expose sensitive pricing, customer data, and company strategy for anyone to read. The dollars at stake can be huge. The average amount in dispute in ICC arbitrations filed in 2023 was about $65 million.
Deadlock needs to connect to a named next step, not a vague promise to sort it out later. If a board deadlock triggers the dispute clause, the draft should say whether the matter goes to executive escalation, an independent expert determination, or an exit path such as a buy-sell or Texas shootout provision. Make the deadlock trigger easy to spot in the draft. Redline the escalation steps, forum, and deadlock trigger before signing.
What to Redline Before the Final Draft
Use this redline checklist to clean up the draft before signature. The seven controls above only work if the language says them in plain English. So before counsel comments, tighten the clauses most likely to spark fights later.
Reserved matters are usually where vague wording turns into veto battles. Terms like “material” or “significant” sound fine at first, but they mean different things to different partners. Swap them out for hard numbers, such as capital expenditures over $750,000 or contracts with a term longer than 36 months, and pair each one with a clear approval standard.
Quorum rules also need a fallback. Without one, a minority partner can stall action just by not showing up. Add an adjourned-meeting fallback and a deadlock trigger so blocking action requires an actual vote, not silence.
Funding obligations and IP ownership need direct fixes, not soft wording. For funding, spell out contribution caps, the call procedure, and what happens if a party doesn’t fund. For IP, use separate schedules for contributed IP, JV-created IP, and post-termination use. If post-termination use is left open, both sides can end up claiming the same technology.
Use the table below to mark the exact clauses that need redlines:
| Drafting Gap | Why It’s Risky | Redline Fix |
|---|---|---|
| Vague reserved matters | Partners interpret "material" differently, causing veto disputes | Itemized list with specific dollar thresholds and approval standards |
| Unclear quorum rules | A minority partner can block action without voting | Add adjourned-meeting fallback and deadlock escalation trigger |
| Open-ended funding obligations | Unpredictable capital calls and disputes over who owes what | Fixed caps, defined call procedures, and dilution consequences for non-funding |
| Undefined IP ownership | Both partners claim rights to JV-developed technology or data | Separate schedules for contributed IP, JV-created IP, and post-termination use |
| Missing audit rights | Non-operating partner cannot verify cash flows or detect mismanagement | Quarterly reporting, books-and-records access, and independent audit right |
| Weak transfer restrictions | Interest sold to a competitor or unwanted third party | ROFR, tag-along/drag-along, and change-of-control consent rights |
| Dispute clause skips escalation | Jumps straight to arbitration, inflating cost and conflict | Tiered clause: management negotiation → executive escalation → mediation → arbitration |
Run this checklist against the draft before counsel comments.
Conclusion
No single clause will protect a joint venture by itself. Strong funding rules don’t do much if the dispute path is fuzzy. Board rights can look solid on paper, then fall flat if the exit terms aren’t there. These seven controls need to work together as one package.
Research points the same way: joint ventures with comprehensive governance frameworks achieve roughly 80% success rates, compared with about 24% for ad hoc partnerships. In plain English, a joined-up draft tends to lead to fewer disputes and clearer execution.
Before signing, test the draft as one system.
That means reviewing the agreement for consistency, not just scanning clauses one by one. Check that each control is specific, lines up across all documents, and fits the guidance from U.S. counsel. For U.S.-based JVs, make sure the draft matches the governing law, venue, data rules, and board expectations.
Peer input from CEO Hangout can help stress-test the draft before signing.
FAQs
Which JV control should I negotiate first?
Start by negotiating the liability structure. Get clear on who handles operations, finances, and compliance, and make sure the JV agreement spells out who carries which risks.
Liability should line up with ownership and day-to-day involvement, with limited-liability protections where possible. That sets the base before you lock in cash controls, board rights, IP and data rules, or exit and dispute terms.
How do I prevent a 50/50 JV deadlock?
Build in deadlock-breaking governance and a clear dispute path before you sign. This is one of those things that feels easy to skip when everyone gets along. Then a hard decision shows up, and suddenly nobody knows who gets the final say.
Spell out decision authority and voting rights in plain terms. A decision matrix or RACI can help divide independent decisions from joint decisions, so people aren’t stepping on each other or stalling work that should move.
You should also set a tie-breaker in advance. That could be a buy-sell option or a neutral advisor with tie-breaking authority. The point is simple: if both sides dig in, there needs to be a path forward.
The dispute clause needs the same level of clarity. Make it step by step: negotiation, then mediation, then arbitration. Add specific timelines and enforceable rules for each stage, so the process doesn’t drag on or turn into a mess.
What should I redline before signing?
Redline these seven JV risk controls before signing:
- Role splits and voting rights: Spell out who does what, who owns which decisions, and which matters need unanimous approval versus a simple majority. If this part is fuzzy, small disagreements can turn into big fights fast.
- Spending limits, funding rules, and monthly reporting: Set clear caps on spending, define when each party has to put in more money, and require monthly financial reporting. That way, nobody gets blindsided by surprise costs or cash calls.
- Liability allocation and cash controls: Put in writing who is on the hook for which losses, claims, or debts. Also lock down how cash is handled, who can move it, and what approvals are needed.
- IP and data rules: State who owns pre-existing IP, who owns anything built during the JV, and how each party can use it. Do the same for data access, storage, sharing, and security.
- Board oversight rights: Define board seats, observer rights, approval rights, and what information the board must receive. Oversight only works when people have both visibility and authority.
- Dispute paths and exit terms: Set the process for disputes upfront, whether that means executive escalation, mediation, arbitration, or court. Then cover exits: buyouts, deadlock terms, transfer limits, and what happens if the JV ends.
Make sure each point is clear, specific, and enforceable in the legal agreement.