

If I use Rule 506(b), I can sell securities without SEC registration, but I cannot advertise the deal to the public. That is the rule in one line.
Here’s the short version:
- I must avoid general solicitation
- I usually sell to accredited investors
- I can include up to 35 non-accredited investors, but that adds more disclosure work
- I need a reasonable belief that accredited investors meet the standard
- If even 1 non-accredited investor joins, disclosure shifts to a much higher level
- I must screen for bad actors under Rule 506(d)
- I usually file Form D within 15 calendar days after the first sale
- The securities are restricted, so investors cannot freely resell them right away
In plain English: Rule 506(b) works best when I keep the deal private, know exactly who the investors are, and keep records that show the offering followed the rule.
A few facts stand out fast. The non-accredited investor limit is 35. Form D is usually due 15 days after the first sale. And resale is limited unless the securities are later registered or fit another exemption. Those three points alone shape how I plan the round, what I send investors, and what counsel checks before closing.
When I look at 506(b), the main issues are simple: who can invest, what I need to disclose, what filings I need to make, and how resale limits work after closing. That is the whole frame of the article, without the extra noise.
Rule 506(b): The Disclosure Reality of a Quiet Raise
sbb-itb-2fdc177
Who Can Invest in a Rule 506(b) Private Placement
Who gets into a Rule 506(b) round shapes more than the cap table. It also affects disclosure, diligence, and what it takes to close. The first call is pretty simple: keep the round limited to accredited investors, or allow non-accredited investors in too.
Accredited investors and the reasonable belief standard
Accredited investors are the main participants in Rule 506(b) offerings. Under Rule 506(b), issuers must document a reasonable belief that each investor is accredited.
That matters because Rule 506(b) does not let issuers treat accredited status as a casual box-checking exercise. The issuer needs records that support its belief.
Non-accredited investors, sophistication, and the 35-investor cap
Rule 506(b) can include up to 35 non-accredited investors, but each one must have enough financial and business sophistication, on their own or through a purchaser representative, to evaluate the investment. Once a non-accredited investor joins the round, disclosure duties expand.
This is where the round can shift fast. On paper, adding non-accredited investors may look like a simple way to widen the pool. In practice, it changes what the issuer has to provide and review.
Why one non-accredited investor changes the round
Adding even one non-accredited investor increases the disclosure package and the compliance burden. In plain English, that one choice can make the round heavier to manage from start to finish.
It determines the disclosure package and the compliance load. And that split leads straight into the disclosure rules that follow.
Disclosure Duties and Information Rights
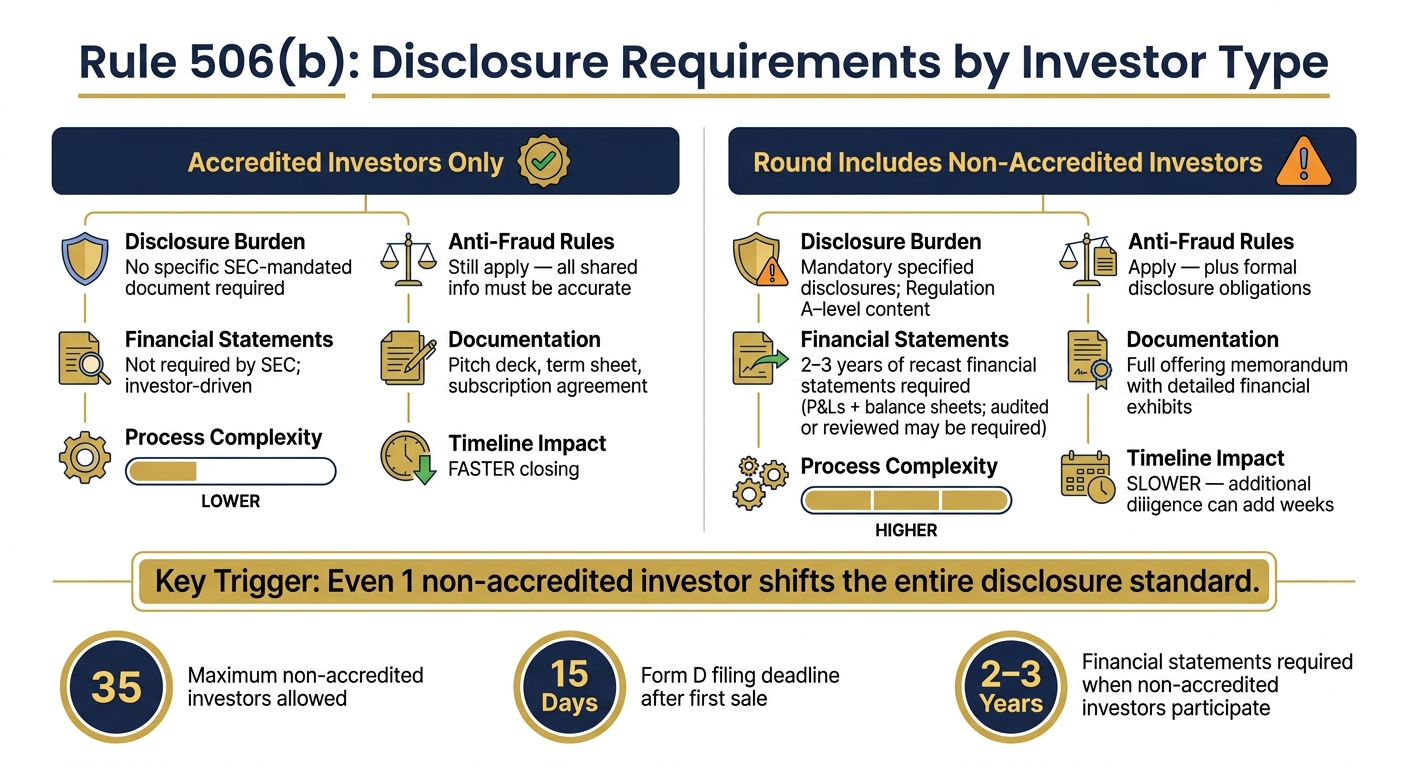
Rule 506(b) Disclosure Requirements: Accredited vs. Non-Accredited Investors
Once your investor mix is set, the disclosure rules start to fall into place. If a round includes only accredited investors, the SEC does not require one set disclosure document. That said, anti-fraud rules still apply, so what you share still needs to be accurate and not misleading.
Bring in even one non-accredited investor, and the bar moves up. At that point, the issuer has to provide much fuller disclosure, at a Regulation A–level standard. That single split changes how much paperwork, review, and detail the round will need.
What must be disclosed when non-accredited investors participate
In an accredited-only round, issuers have more room in how they present information. There is no SEC-required disclosure package, even though anti-fraud rules still apply.
Once any non-accredited investor participates, the issuer must deliver an offering memorandum or similar disclosure package. That package needs to cover business details, entity structure, operating history, and 2–3 years of recast financial statements, including P&Ls and balance sheets. Audited or reviewed financials may also be required.
Equal access to information and investor questions
After the disclosure package, the next issue is consistency. Non-accredited investors must get the same information accredited investors get, including access to pitch decks, data rooms, and management Q&A sessions.
That means your decks, emails, data room files, and investor calls should line up. If one investor hears something material, the others should not be left in the dark. A CRM can help track investor communications so follow-ups stay on time and no investor gets materially different information than another.
Disclosure expectations by investor type: a comparison
This split is easier to see side by side:
| Feature | Accredited-Only Round | Round Including Non-Accredited Investors |
|---|---|---|
| Disclosure Burden | No specific SEC-mandated document; anti-fraud rules apply | Mandatory specified disclosures; Regulation A–level content |
| Financial Statements | Generally not required by the SEC; investor-driven | 2–3 years of recast financial statements |
| Documentation | Pitch deck, term sheet, subscription agreement | Offering memorandum with detailed financial exhibits |
| Process Complexity | Lower | Higher; requires formal disclosure drafting and verification |
| Timeline Impact | Faster | Slower; additional diligence can add weeks |
Bad Actor Checks, Form D, and Resale Limits
Bad actor screening, Form D, and resale limits are final closing checks, not loose ends to deal with later. Once disclosure is settled, counsel usually turns to three things before money changes hands.
Rule 506(d) bad actor disqualification review
Under Rule 506(d), an issuer has to screen all covered persons for disqualifying events before the offering closes. That group includes the issuer, directors, executive officers, participating officers, promoters, and compensated solicitors.
A disqualifying event can knock the offering out of Rule 506 protection. Common examples include a securities conviction, an injunction, or an SEC order. And there’s a catch: events that happened before the rule took effect may still trigger a written disclosure duty.
Once that review is done, counsel usually moves to the federal notice filing.
Form D filing after the first sale
Issuers generally must file Form D with the SEC within 15 calendar days after the first sale of securities in the offering. Form D is a notice filing, but that doesn’t mean it’s minor. A late filing, or one that doesn’t line up with the rest of the deal record, can create headaches in later fundraising rounds.
There’s also a state layer to deal with. Many states require their own notice filings and fees, so counsel should line up the federal and state filings before the first sale closes.
The last check is more practical: how the securities will be labeled and transferred after closing.
Restricted securities and limits on resale
Unregistered restricted securities can’t be freely resold unless they’re registered or fit within an exemption. In plain English, investors usually shouldn’t expect to turn around and sell them right away.
That’s why you’ll usually see:
- restrictive legends on the securities
- stop-transfer instructions
Put those resale limits in writing before closing. It sets expectations early and makes it clear that the securities are not immediately tradable.
Closing Review With Counsel and Key Takeaways
What leadership should confirm before closing the round
Once eligibility, disclosure, and resale limits are set, there’s one last checkpoint: a counsel-led closing review.
Before closing, leadership should review six things with counsel:
- Confirm no general solicitation or public advertising took place.
- Verify investor counts and make sure the 35 non-accredited investor cap was not exceeded.
- Confirm each non-accredited investor was reviewed for sophistication.
- Confirm the disclosure package is complete and delivered.
- Complete and retain Rule 506(d) screening records.
- Confirm subscription documents are fully signed, restrictive legends and resale acknowledgments are in place, and Form D plus any required state notice filings are scheduled after the first sale.
This final check is there to catch problems before any money moves.
Before signing vs. before taking funds
Timing matters. Some items need to be buttoned up before signatures. Others need one last check before money is accepted or securities are issued.
| Action Item | Before Signing Offering Documents | Before Accepting Funds / Issuing Securities |
|---|---|---|
| Investor questionnaires | Verify all questionnaires are complete and confirm accredited status. | Re-confirm that there have been no material changes in investor status. |
| Disclosure package | Finalize the PPM or disclosure materials. | Confirm all investors received and acknowledged any material updates. |
| Subscription documents | Counsel reviews subscription agreements, warrant terms, and conversion terms. | Verify all signature pages are complete and escrow is ready. |
| Rule 506(d) screening | Complete Rule 506(d) review for all covered persons. | Perform a final re-check to confirm no new disqualifying events have occurred. |
| Transfer restrictions | Draft restrictive legends for stock certificates or book-entry positions. | Confirm investors signed acknowledgments about resale limits and hold periods. |
| Regulatory filings | Identify required state securities notice filings and federal Form D. | Confirm wiring instructions are accurate and escrow is ready. |
Once those items are done, the round is ready to close under Rule 506(b).
Conclusion: The main compliance points under Rule 506(b)
Rule 506(b) is a private offering process. Leadership needs to document who the investors are, what they were told, and why the round fits the rule.
Disclosure duties shift based on the investor mix. If non-accredited investors are included, the standard gets much stricter. Closing also means finishing Rule 506(d) screening, making timely Form D and state securities notice filings, and putting restricted securities plus resale acknowledgments in place.
Leadership should review the full process with qualified securities counsel before the first dollar changes hands.
FAQs
What counts as general solicitation?
In a Rule 506(b) private placement, general solicitation means publicly advertising your securities. Since Rule 506(b) bars that, startups using this exemption can’t promote the offering to the public when trying to raise capital.
To stay compliant, skip broad public outreach. Stick to established networks and existing relationships instead.
How do I verify accredited investor status?
Under Rule 506(b), investors can self-certify by filling out an accredited investor questionnaire.
In plain English, an individual will usually qualify as an accredited investor if they meet the SEC’s standards for wealth, income, or professional licenses. That can include:
- A net worth of at least $1,000,000, not counting a primary residence
- Annual income of $200,000 on their own, or $300,000 with a spouse, for the prior two years, with the same income expected this year
- Certain professional licensure criteria recognized by the SEC
If an investor is not accredited, you need to confirm that they are sophisticated enough to assess the risks of the investment.
What if one non-accredited investor joins?
Under Rule 506(b), a startup can include up to 35 non-accredited investors in a private placement.
If even one non-accredited investor joins, the startup has extra work to do. It must confirm that the investor is sophisticated enough to judge the deal’s risks and merits, provide the required financial disclosures, and stay available to answer questions throughout the process.